Skip to content

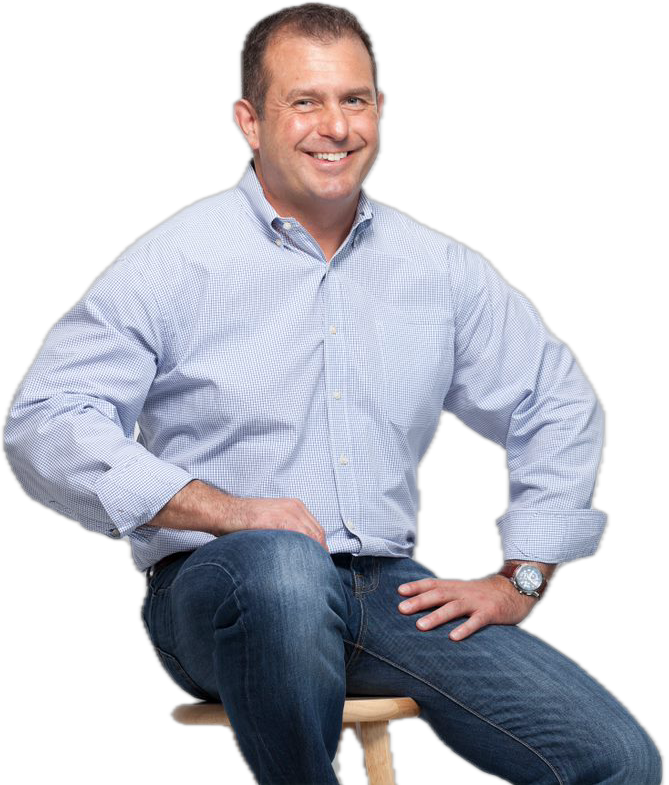
Hi, I'm Jack…

Jack Flynn

We make the mortgage process simple by teaching you every step.

Jack Flynn
Get started

Ways Jack Can Help

Whatever stage you're at, there's a straight answer waiting instead of a sales pitch.

Meet Jack Flynn

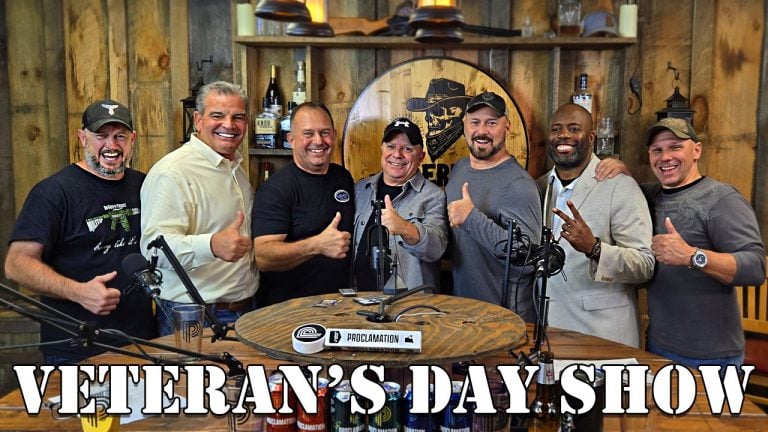
Combat veteran. Coach. Educator.
Twenty years teaching people the mortgage process before they sign anything.

Our Core Values

We strongly believe the way we do things is just as important as the things we do. Every team member is guided by our Core Values, which define how we work, how we interact with each other, and in determining how we best serve our clients, team members, and our local communities.

Reviews reflect individual experiences and are not a guarantee of loan approval, rates or terms.

What Clients Say

Real reviews from people Jack has helped buy and refinance, word for word.

Jack was tremendous to work with. He communicated consistently throughout the whole process of working with Fairway, is personable, experienced , and always willing to hop on a call and explain something. I couldnt have had a better lender for my first home buying experience thanks to him. I would 100% recommend him to anyone going forward.

Megan E S East Providence, RI · May 2025

Jack is extremely knowledgeable. The whole experience during my refinance was quick and easy, zero stress! He helped me through every step of the process. 10/10 recommend!!

Melissa B Warwick, RI · February 2025

The process was very stressful for me but Jack made it smooth. He knew my goal from the very beginning and made it sure that I achieved it.

Vanessa B Attleboro, MA · November 2024

Read all 34 reviews

Background

Army National Guard, 26 Years of Service

Infantry Combat Veteran, Afghanistan (OEF)

20+ years

In the mortgage business

Local Office - East Greenwich, RI

Adjacent to Camp Fogarty
National Guard Base

Vice President

Narragansett Lions Club

College of the Holy Cross Rugby

Assistant Coach: Mindset, Culture & Development

This Is Personal

Jack served 26 years in the Army National Guard, including combat deployment to Afghanistan. Heroes Way Home is how he gives that back — a dedicated path for veterans, active-duty service members, and first responders to use the VA loan benefit they earned, guided by someone who's walked the same road.

Explore Heroes Way Home
Let's Do It!

Mortgage insights and strategies

Read All Blog Posts

See What Your Equity Could Look LikeAnd When It Overtakes What You Owe

Set your price, your down payment and a rate you want to test, then watch the two lines move. Jack will run the real numbers with you when you are ready.

Your numbers

Purchase date
Home value Loan balance Your equity
Sell in year 5

Projected at sale
Home value $0
Remaining loan balance $0
Gross equity $0
Estimated selling costs $0
Estimated net proceeds $0
This is an educational estimate, not a loan offer. Read more

The figures shown are illustrations produced from the numbers you enter. They are not a quote, a rate lock, an approval, a commitment to lend, or a guarantee of future property value.

Appreciation is applied as a steady annual rate for illustration. Real property values move unevenly and can fall. The projection excludes property taxes, insurance, mortgage insurance, homeowner association dues, maintenance, and any capital gains tax that may apply to a sale. Selling costs are your own estimate.

Actual loan terms depend on a complete application, credit review, property appraisal, and program eligibility. Speak with Jack before making a decision based on anything here.

We'll help you find
all the mortgage answers you need

How much can I afford to borrow?

Your approval amount and your real budget are two different numbers. Approval is based on income and debt; budget is based on what you're actually comfortable paying every month. Jack covers both before you start touring homes.

Numbers First. Decisions Follow.

How much should I put down on a home?

It depends on the loan type. Some programs allow far less than the 20 percent most people assume is required, including options with little to no down payment for eligible veterans. Numbers first. Decisions follow.

What are the different types of mortgages?

There are several types of home mortgages, each designed to meet different financial circumstances and homeownership goals. The right mortgage depends on your credit, income, down payment, property type, and long-term financial plans.

Conventional Loans: Popular financing options for borrowers with established credit and stable income. Conventional loans can offer flexible down payment options, including as little as 3% for eligible buyers.

VA Loans: Available to eligible veterans, active-duty service members, and certain surviving spouses. VA loans offer significant benefits, including the possibility of purchasing with no down payment and no monthly mortgage insurance.

FHA Loans: Government-insured mortgages that may be attractive to buyers with lower credit scores or limited down payment savings. Eligible borrowers may qualify with as little as 3.5% down.

USDA Loans: Designed for eligible homebuyers purchasing in qualifying rural and suburban areas. USDA programs may provide 100% financing, subject to income, property, and other eligibility requirements.

Jumbo Loans: Financing for higher-priced homes that exceed conforming loan limits. These mortgages typically have different credit, income, asset, and reserve requirements.

Construction and Renovation Loans: Specialized financing that may allow borrowers to build a new home, purchase a property needing improvements, or renovate their existing home.

Reverse Mortgages: Available primarily to homeowners age 62 or older, these loans allow eligible borrowers to access home equity without required monthly principal and interest payments. Borrowers remain responsible for property taxes, insurance, maintenance, and other loan obligations.

Fixed-Rate and Adjustable-Rate Mortgages: These describe how your interest rate works rather than a separate mortgage program. A fixed-rate mortgage maintains the same interest rate throughout the loan term. An adjustable-rate mortgage may change after an initial fixed-rate period.

At Heroes Way Home, we help you compare mortgage programs, monthly payments, upfront costs, and long-term financial implications.

The best mortgage is not necessarily the one with the lowest interest rate. It is the one that fits your financial circumstances and future goals.

Numbers First. Decisions Follow.
What is PMI and when is it required?

Private mortgage insurance is typically required when a down payment is below 20 percent on a conventional loan. It protects the lender, not the borrower, and Jack can explain how to avoid it or remove it later.

What is the difference between a pre-approval and a pre-qualification? And what is the Fairway Advantage Credit Appproval?

Not all mortgage approvals are created equal. Understanding the difference can make a significant impact when you're ready to purchase a home.

**1. Pre-Qualification: An Initial Estimate**

A pre-qualification is a preliminary estimate of what you may be able to afford, generally based on financial information you provide. It is a useful starting point, but your income, assets, and credit may not have been fully verified.

**2. Pre-Approval: A Stronger Position**

A pre-approval typically involves reviewing your credit, income, assets, and financial obligations. It provides greater confidence in your purchasing power and demonstrates to sellers that you have taken meaningful steps toward obtaining financing. However, it is generally not a final underwriting decision.

**3. Fairway Advantage: Underwritten Credit Approval**

Fairway Advantage takes the process further. Your financial information is reviewed by an actual mortgage underwriter before you find a home.

This means your creditworthiness has already undergone a comprehensive underwriting review, with final loan approval still subject to property requirements, acceptable loan terms, and other applicable conditions.

**Why does this matter?**

In a competitive housing market, a fully underwritten credit approval can help strengthen your offer, provide greater confidence to sellers, and reduce financing uncertainty.

At Heroes Way Home, we believe preparation creates opportunity. Our goal is to help you understand your purchasing power and put you in the strongest possible position before making an offer.

**Numbers First. Decisions Follow.**

What is the mortgage application process like?

In general: pre-approval, house hunting, offer and contract, full loan application, underwriting, and closing. Jack walks you through each step so nothing catches you off guard.

Still have a question?

Type it in — we'll try to answer it right away, and it helps other visitors too.

Can't find an answer?
Jack will walk you through it directly.

Schedule a conversation
Jack Flynn
Jack Flynn Branch Manager, Certified Mortgage Advisor

Schedule Consultation

Let's Do It!

Equal Housing Lender. Jack Flynn, CMA Branch Manager, Certified Mortgage Advisor · NMLS #1243317 · (401) 569-3731 “Numbers First. Decisions follow.”

Entity and Licensing

Customer Service and Reporting

Sign in